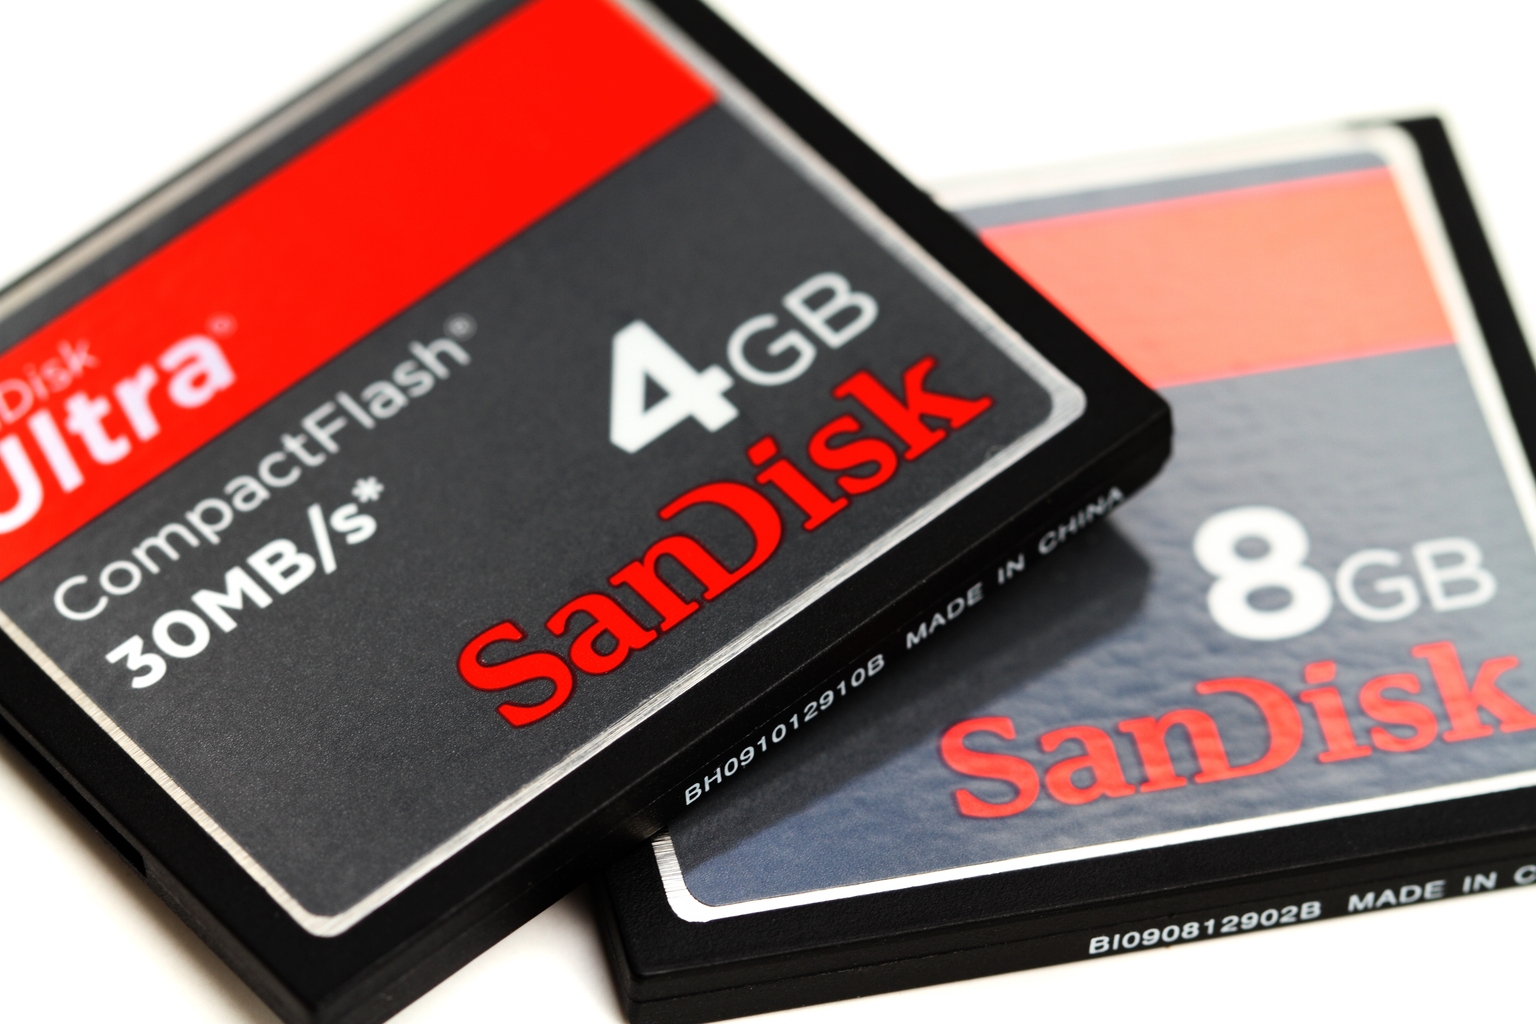
Normally I would look at SNDK's earnings reports, its cash position, its debt position, its customer commitments, its industry getting wise to how it can leverage pricing power for longer, and its decision to do an 8:1 split as a decent opportunity to get…