Home
Earnings Analysis
Consumer
Summary
BJ's Restaurants remains a 'Buy' pre-earnings, offering double-digit upside and mid-single-digit buybacks.
FY 2026 guidance calls for 1–3% same-store sales growth and EBITDA margins of 9.6–10.3%, well above historical averages.
Capex compression in FY 2026 turns BJRI into a short-term cash cow, with $27–50 million FCF likely fueling buybacks.
Valuation at ~8.6x EBITDA appears attractive, reflecting a shift from high growth to steady profitability and margin expansion.
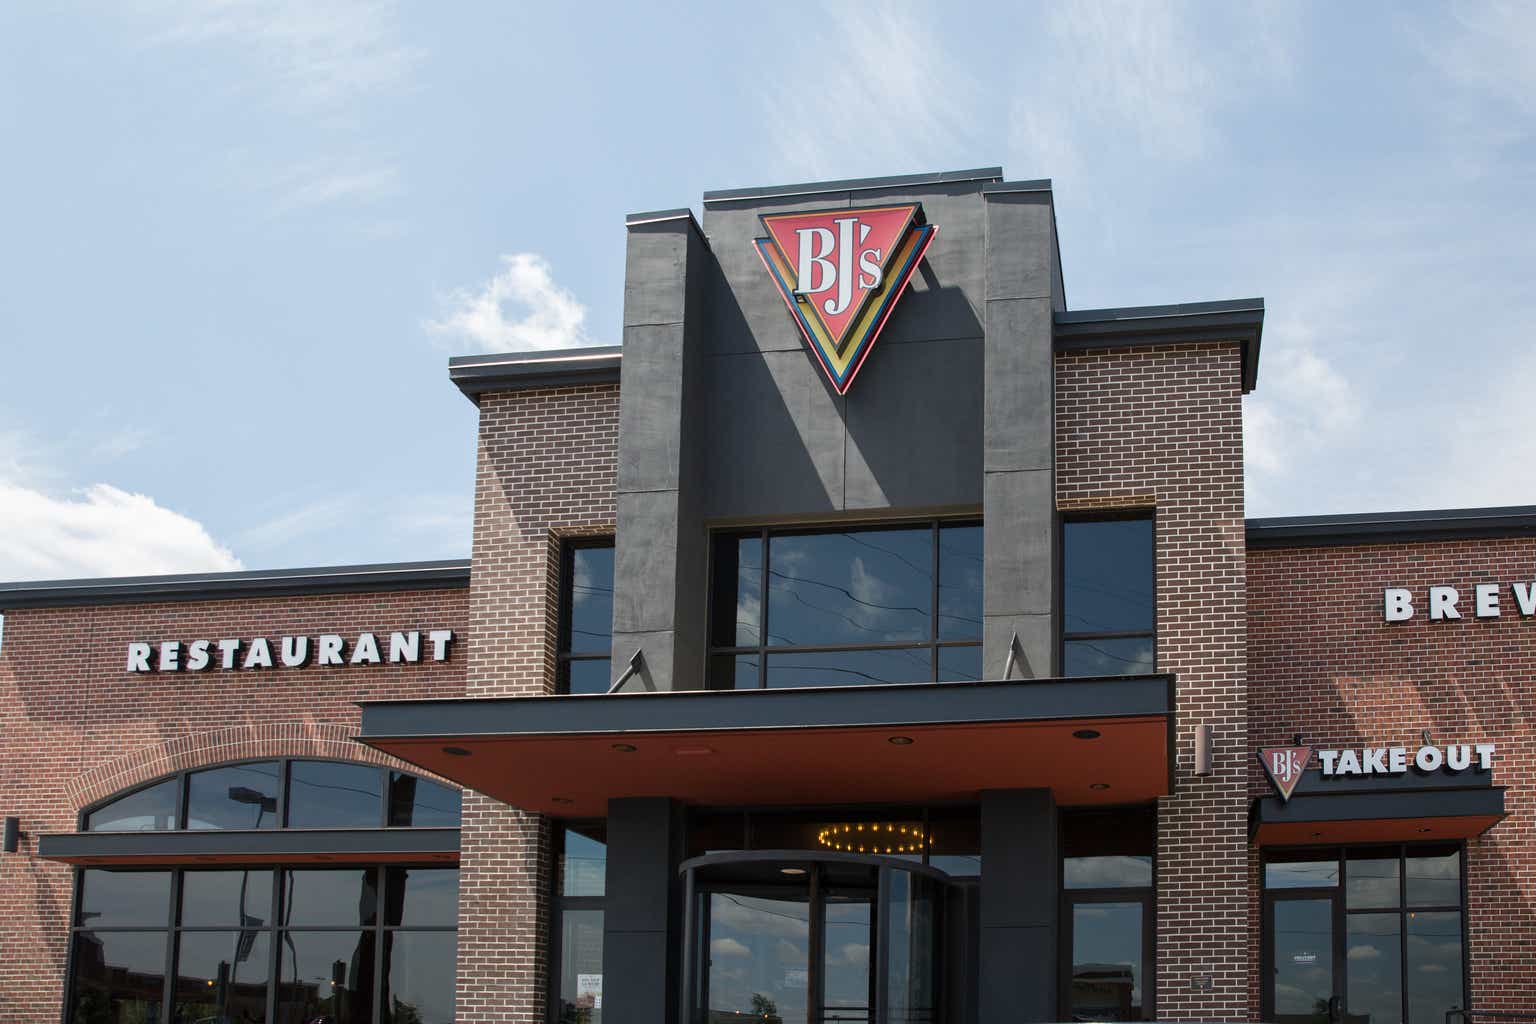
helen89/iStock Editorial via Getty Images
Time flies when we're having fun, doesn't it? It seems like only yesterday I flagged you up about another 'Pizookie Dip' for BJ's Restaurants ( BJRI ).
And this California-based chain continues to sit in highs
Analyst’s Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no plans to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions.…