Seeking Profits 5.77K Followers
Summary
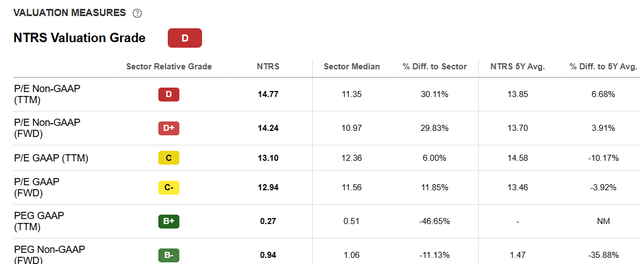
Northern Trust shifts from 'sell' to 'hold' as valuation premium narrows and capital return remains robust.
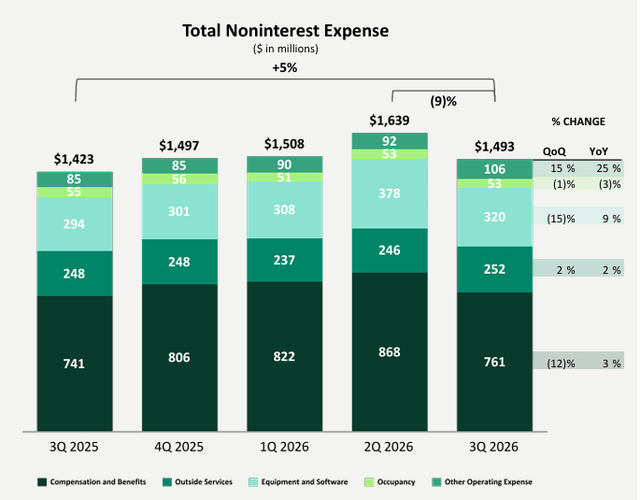
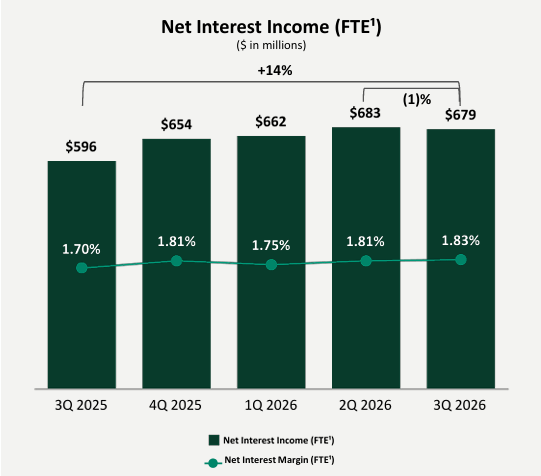
Fee income and net interest margin benefit from rising markets and rates, while cost discipline drives margin expansion.
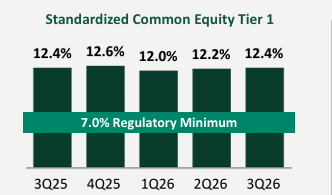
NTRS’s strong CET1 ratio and active buybacks support a secure 2.1% dividend and near-100% earnings return to shareholders.
Earnings outlook improves to at least $13.25 next year, but there is muted long-term growth and commoditized business cap upside.
hapabapa/iStock Editorial via Getty Images
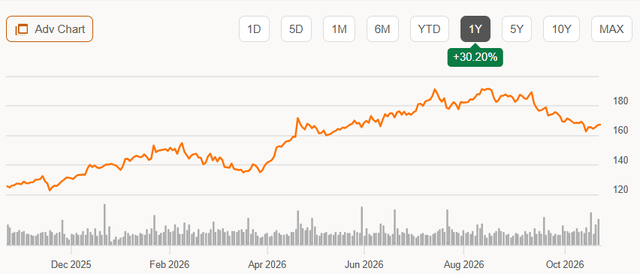
Shares of Northern Trust (NTRS) have been a solid performer over the past year, rallying about 30%. The company, like the other trust banks State Street (STT) and BNY Mellon (BNY), has benefited from a favorable macro environment. Rising markets boost fee income, and the rate environment is supporting solid interest income. Beyond this, NTRS's cost-cutting efforts have made progress.…