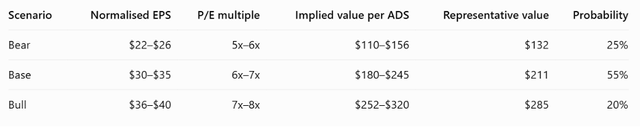Future Stack Investment 958 Followers
Summary
SK hynix is rated 'Buy' due to strong AI memory positioning, robust cash flow, and attractive valuation upside.
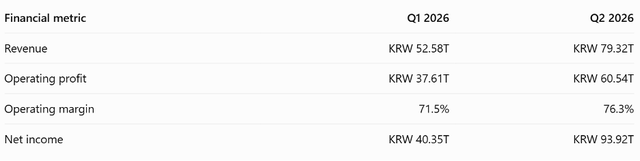
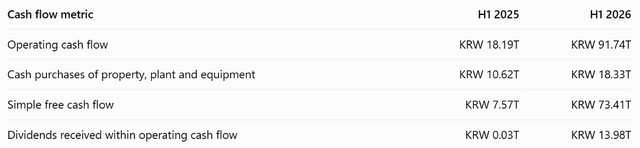
Q2 saw record profits, but core business cash conversion and capital discipline are critical for sustainable shareholder returns.
Management commits to returning over 50% of cumulative free cash flow from 2025–2027, with a probability-weighted fair value of ~$206/ADS.
Risks include cyclical memory pricing, ongoing heavy investment needs, and competitive pressure from Samsung and Micron.
Richard Drury/DigitalVision via Getty Images
Elevator Thesis
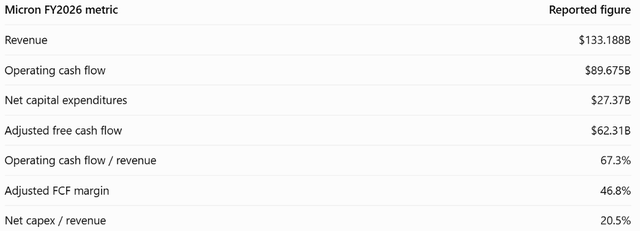
My recent Micron (MU) piece got me thinking about a bigger question.
The numbers show that strong AI requires a lot of memory. The key is how much cash these companies keep after they've paid for fabs, equipment, and working capital.
That is what I will be looking at with SK hynix Inc. (SKHY).…