Intrinsic Analysis 656 Followers
Summary
Barclays PLC is upgraded to Buy after a recent 20% share price decline driven by potential U.K. bank tax hike concerns.
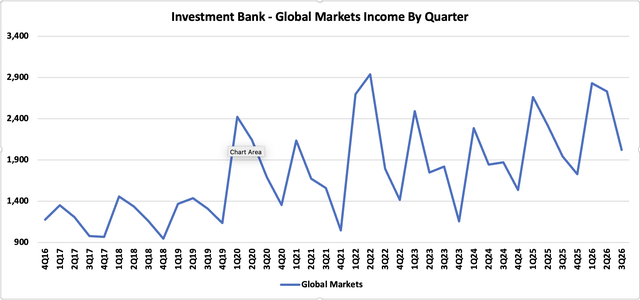
Investment Bank Q3 income lagged consensus driven by weaker global markets' income.
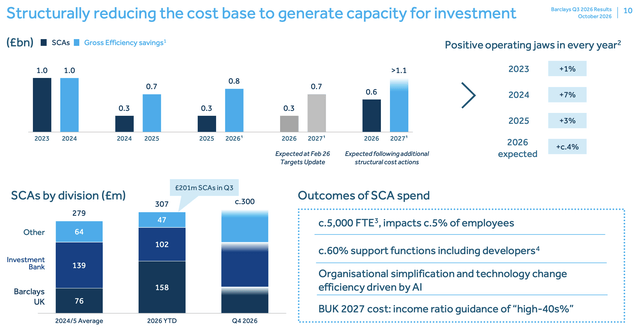
AI-driven efficiency gains are enabling a 5% workforce reduction and supporting cost-to-income ratio improvements in the U.K. segment over FY27 and FY28.
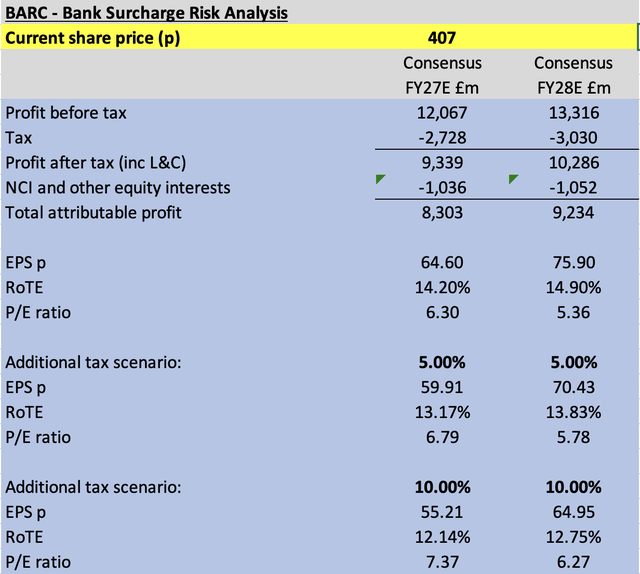
At a forward P/E below 7x and trading slightly below tangible net asset value, BCS offers compelling medium-to-long-term value despite near-term tax policy risks.
Dilok Klaisataporn/iStock via Getty Images
Introduction
In early August, I downgraded Barclays PLC (BCS) to Hold, highlighting revenue headwinds, unexpected cost pressures and the risk of higher U.K. bank taxes. Several of the issues that I flagged in August have subsequently become front-of-mind topics for the market.…