Home
Stock Ideas
Long Ideas
Real Estate Analysis
Summary
LandBridge maintains robust growth and margins through strategic surface acreage acquisitions and a low-cost, diversified business model.
Q1 2026 revenue rose 16% YoY to $51M, with operating margin expanding to 57.4%, demonstrating strong operational leverage despite increased expenses.
LB's royalty-based model and expanding surface acreage position it to benefit from higher oil prices and potential demand influx in the US energy sector.
I reiterate my buy rating, citing reasonable valuation (TP $74.42), solid liquidity, moderate leverage, and multiple buying opportunities despite cautious technicals.
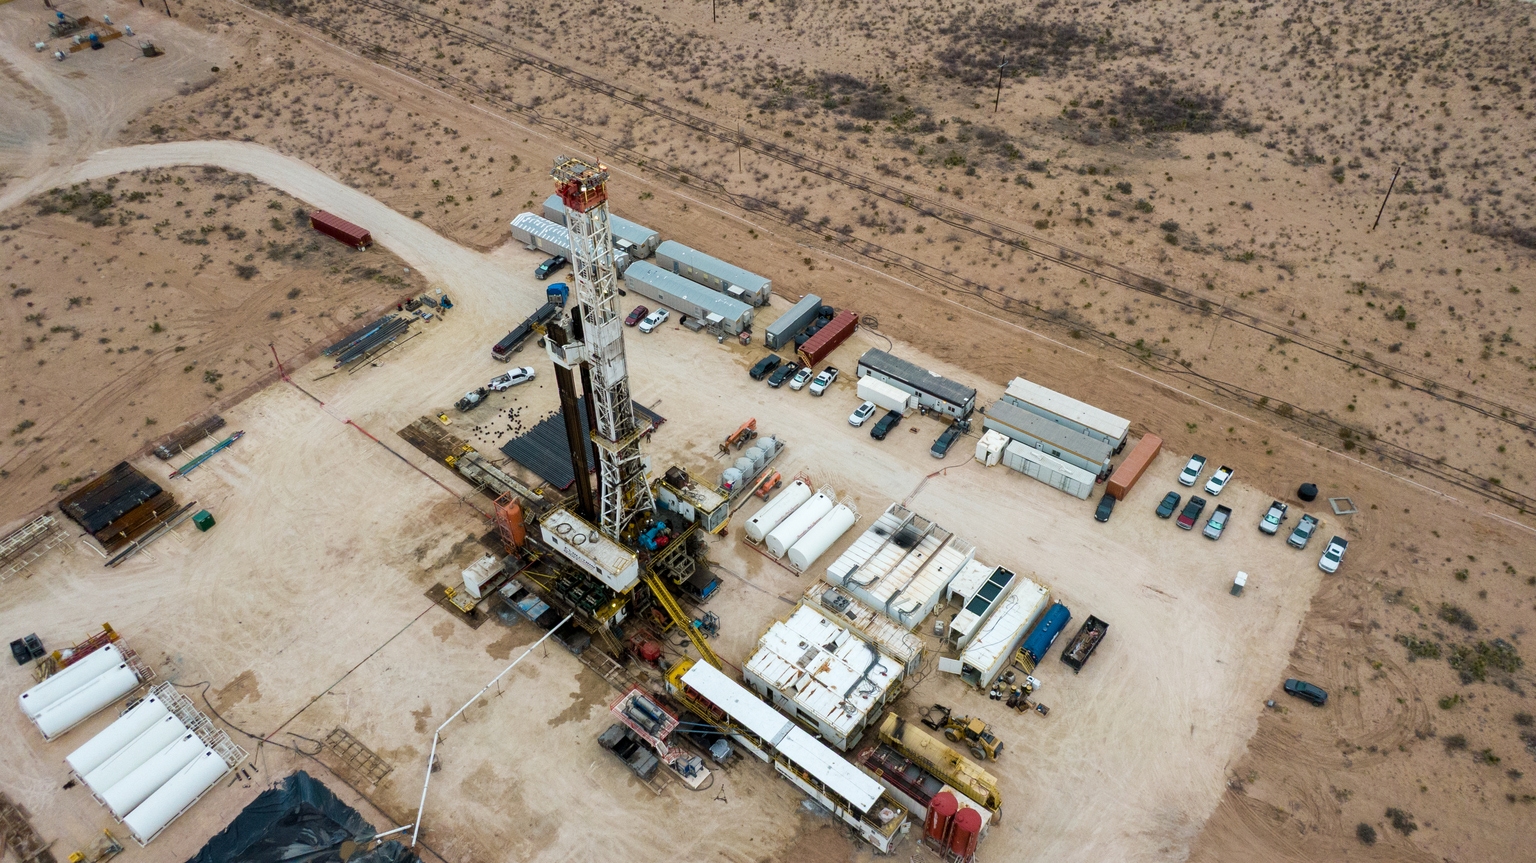
Joey Ingelhart/iStock via Getty Images
It has been a year since my initial coverage of LandBridge Company, LLC ( LB ). A lot has happened in the global oil and gas market, leading to its sharp price swings.…