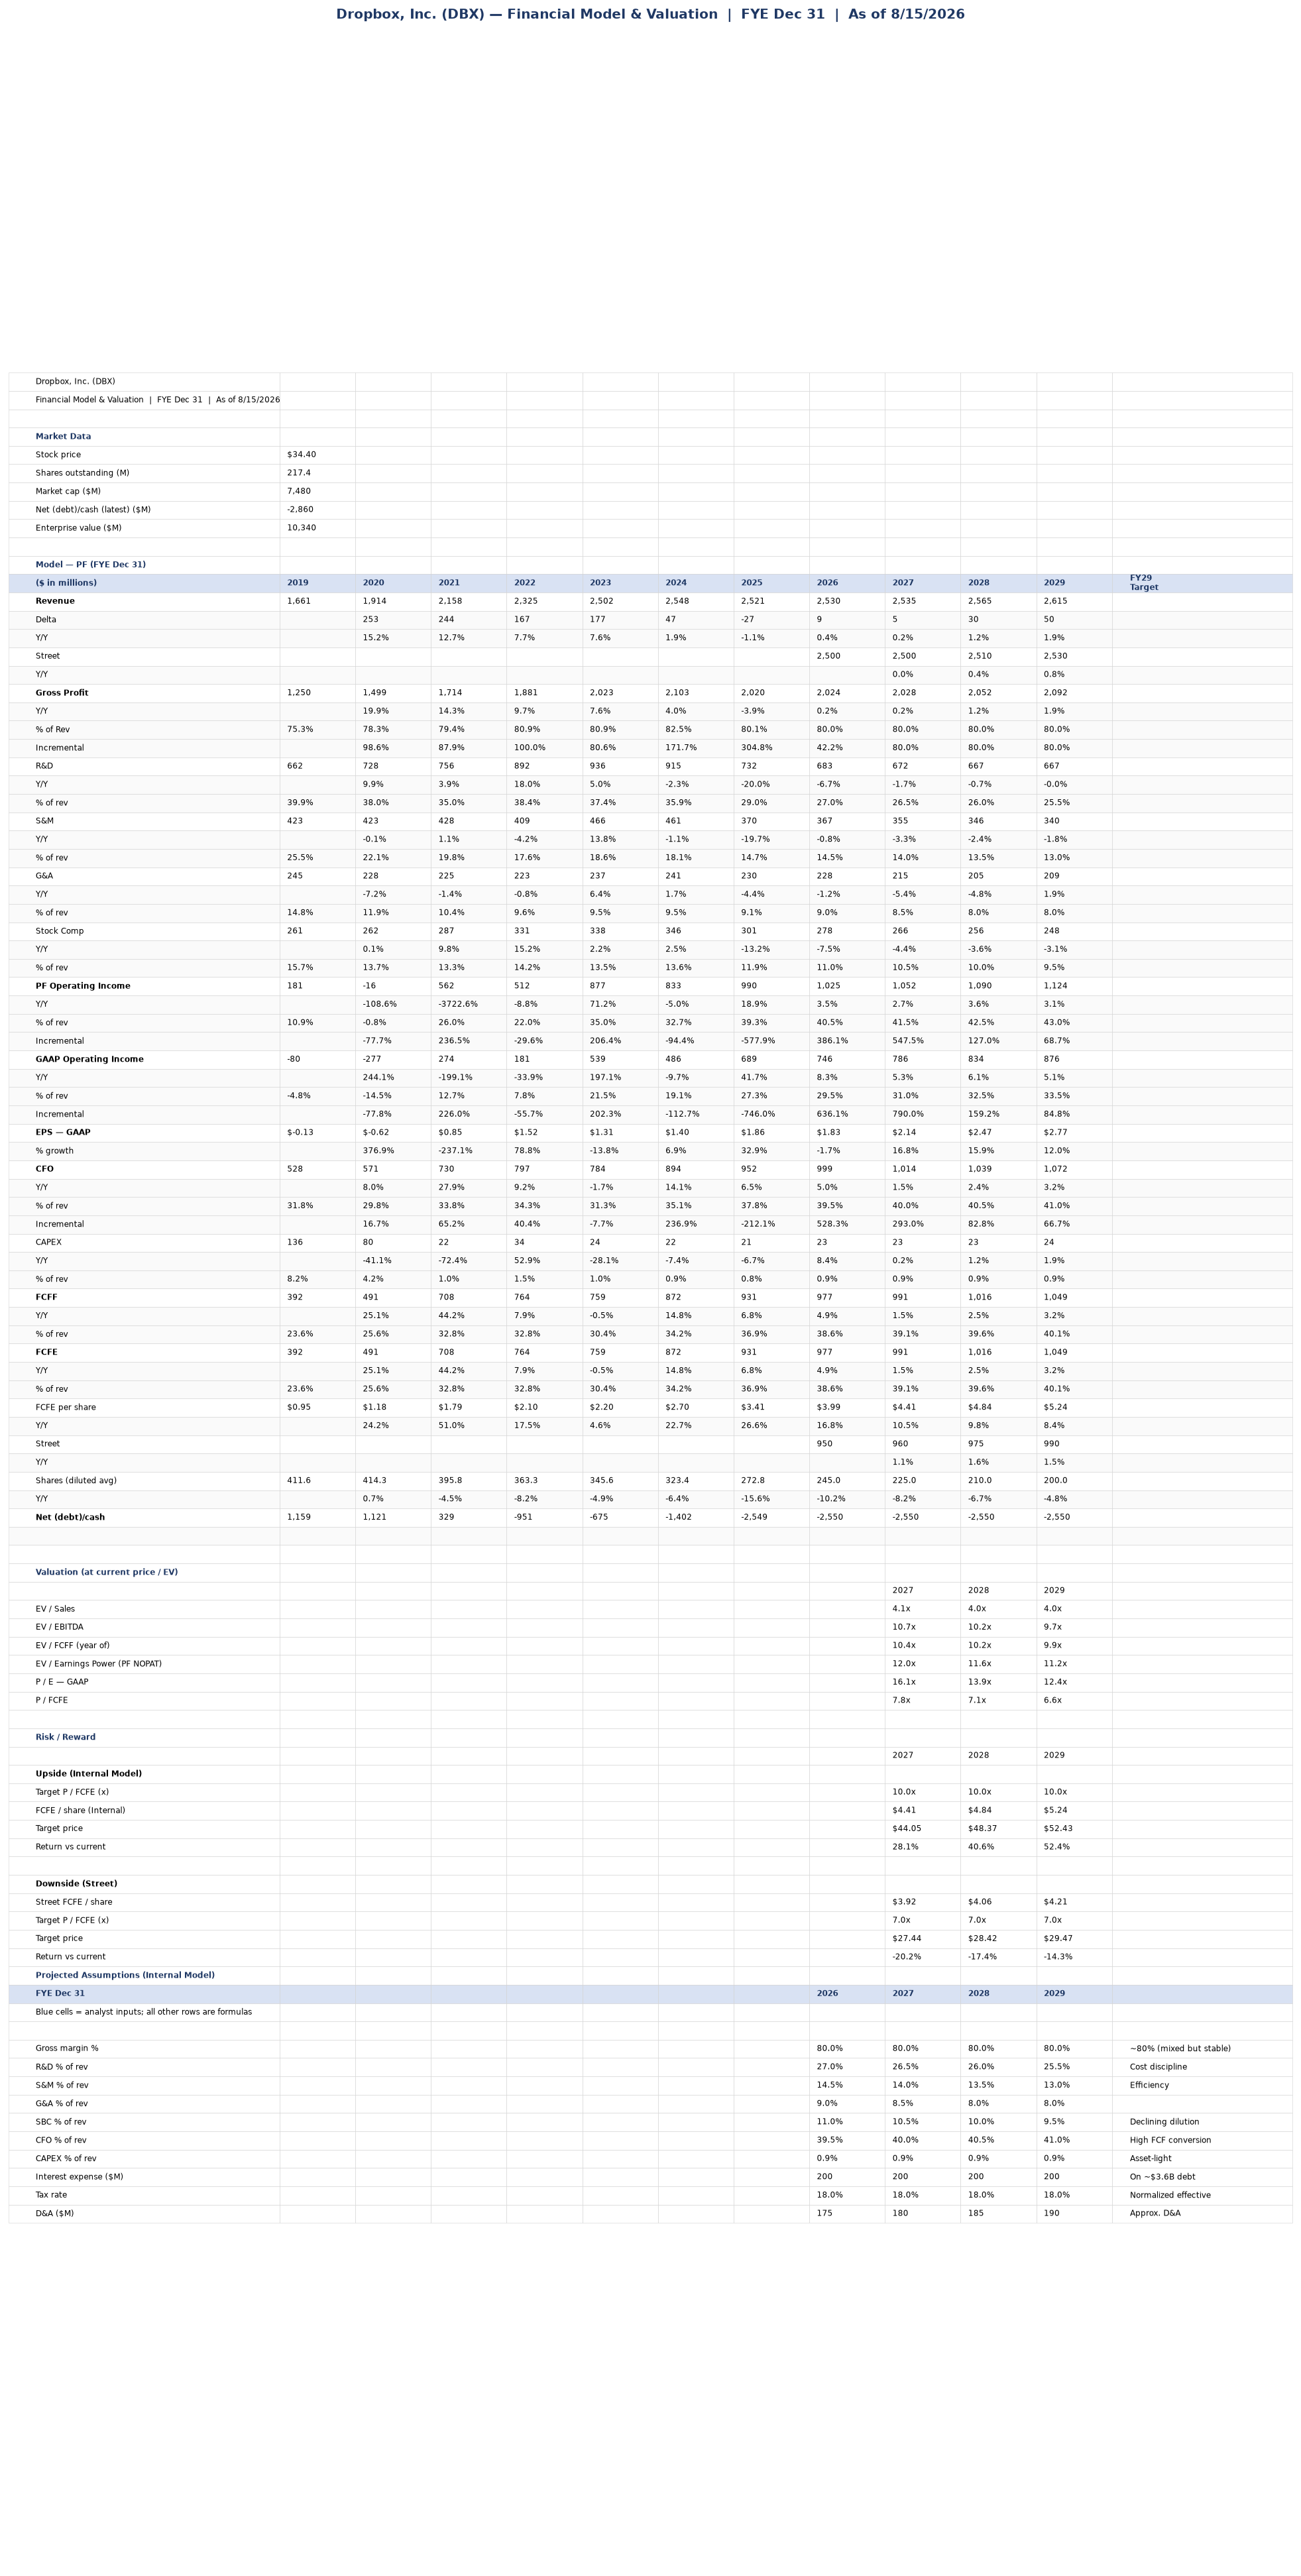
I have been doing research on companies, reading 10-Ks, etc. But as of late, reading the 10-K and seeing the slowing growth, there was not much to be optimistic about. Again, Steve Jobs was right: Dropbox was indeed a feature, not a Product, and clearly the wave of enterprise companies that were features that IPOed and struggled is many. Thus, I have a thesis of a wave of consolidation in this sector. And SaaS generally has had a history of strategic consolidation. Dropbox would not be a strategic acquisition since most of the major enterprise companies already have a solid storage business. But it does throw off cash, and a lot of it. In FY2025, it threw off 931 million in free cash flow. From a Hamilton Hemler perspective, their main power is to allow for sustainable long-term cash flow, which would be switching costs.…