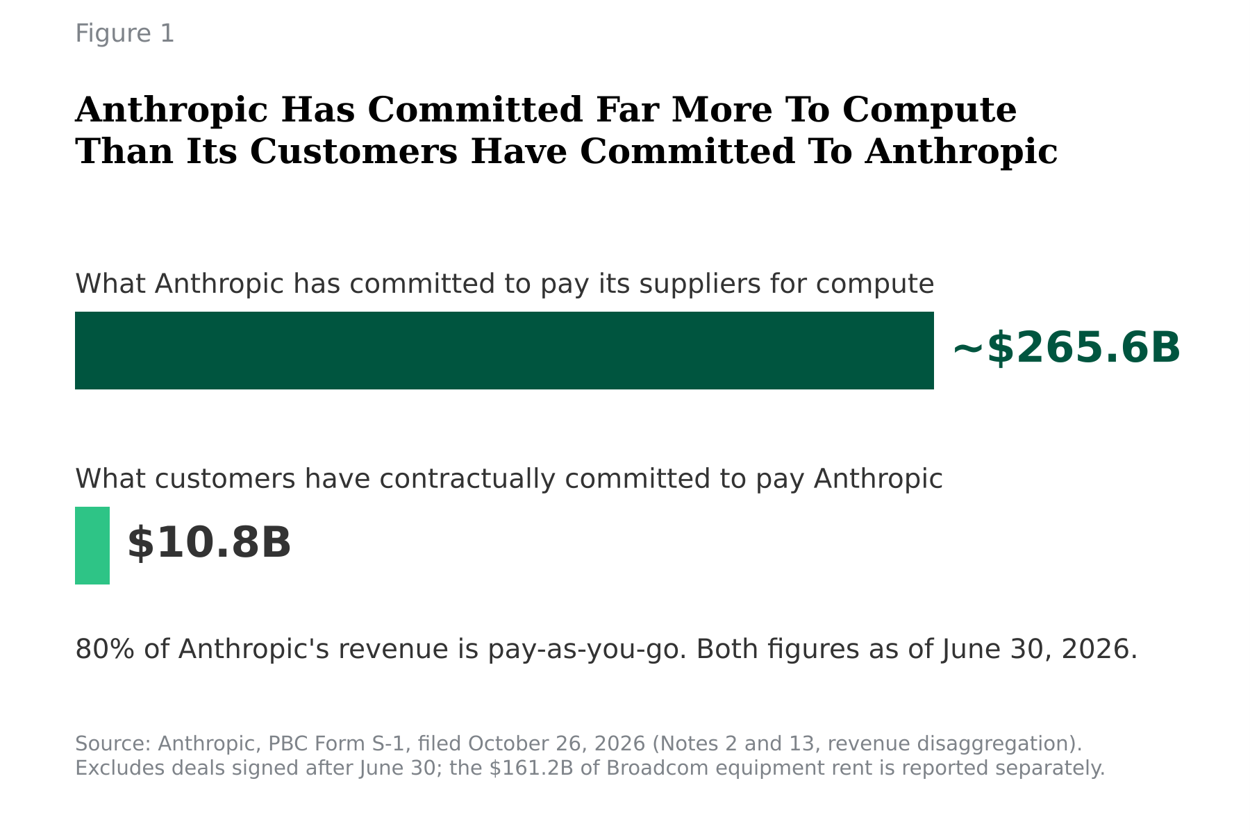
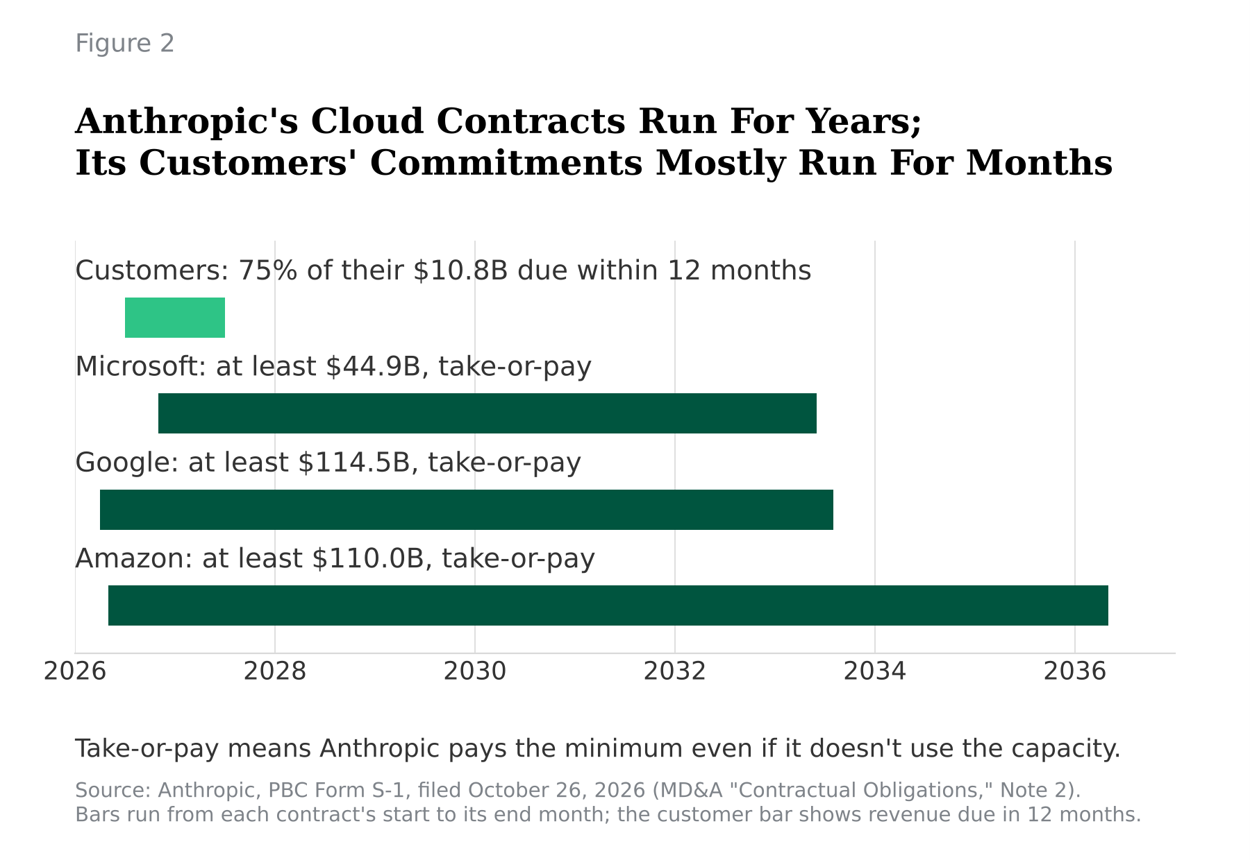
Back in June, we argued that Anthropic’s proposed IPO would change the economics of enterprise AI , reasoning that a public listing brings discipline: Pricing would “get real,” capital would chase acquisitions, and Anthropic would trade capability for cost. The public S-1 , filed October 26, has the numbers we lacked a few months ago, and it did change our minds on three of those calls. A bigger issue emerged when we compared its compute purchase commitments with the kind of revenue it earns. After reviewing the S-1, we think:
Pricing will get “real” … by getting cheaper. Serving AI already makes Anthropic money. Its gross margin was 85% in the first half of 2026 by our math, up from 12% a year before, and the newest model cut customers’ cost per task about 40%. And as we explain below, it needs low prices to fill the compute capacity it has committed to.
Anthropic won’t slow research to improve its margins. In June, we expected it to favor cost-efficiency over capability growth.…